Car Buyers Urged to Compare Total Financing Cost, Not Just Monthly Instalments
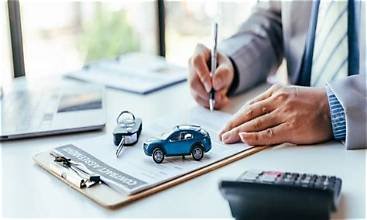
Dubai: Experts have urged car buyers in the UAE to look beyond monthly instalments when choosing vehicle financing and compare the total amount they will pay throughout the contract.
Dealership-linked financing and affiliated finance companies may offer faster approvals and more flexible terms in some cases. However, experts warn that easier approval or a lower monthly instalment does not necessarily mean a lower overall cost.
The final amount may increase after adding interest or profit charges, processing fees, insurance, maintenance contracts and any final payment. Customers are therefore advised to understand the cash price of the vehicle as well as the total deferred or financed price before signing an agreement.
UAE Central Bank regulations set the maximum car financing limit at 80% of the vehicle's value and the repayment period at no more than 60 months. Consumer protection standards also require licensed financial institutions to provide key information, including the annual percentage rate (APR), interest or profit calculation method and applicable fees.
Banking expert Amjad Nasr advised customers to compare four important figures before signing a financing contract: the vehicle's cash price, the down payment, the total instalments and all fees and charges.
He explained that customers who face bank financing difficulties because of high financial commitments or credit-record issues may consider alternative financing. However, faster or easier approval can come with a higher overall cost.
For example, a vehicle with a cash price of AED 100,000 could cost AED 120,000, AED 130,000 or more after financing and associated charges. The total amount payable should therefore be considered the true financing cost.
Experts recommend that customers carefully review ownership conditions, early settlement terms, fees and the overall amount payable before selecting a vehicle financing option.
Photo Gallery